Debt restructuring changes loan terms when a borrower cannot meet obligations or needs a short-term break to recover. Lenders may use it to improve repayment prospects and avoid a larger loss. section 4.2.1
Possible adjustments include:
- Reducing the interest rate. section 4.2.1
- Extending the loan maturity. section 4.2.1
- Writing off part of the debt. section 4.2.1
AI-based forecasting can help lenders estimate which restructuring approach is likeliest to succeed for a borrower. Risk-based adjustments should be fair and consistent, with decisions documented. section 4.2.1 section 4.2.1
Figure 4.1 The three key phases of the loan life cycle, pre-loan, in-loan, and post-loan, apply to both personal and corporate credit products. Each phase contains distinct activities, decision points, and opportunities for AI-enhanced risk management.
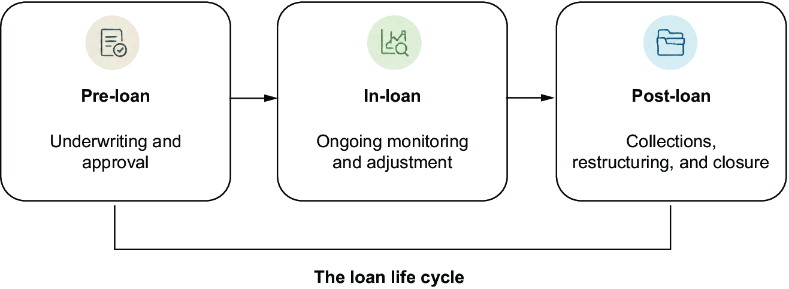
Shows restructuring within the post-loan phase of the loan life cycle. section 4.2.1
