Option pricing estimates the value of contingent financial payoffs. In tax-loss harvesting, it quantifies the opportunity cost of being unable to switch back to a primary ETF for 30 days after selling it at a loss. section 14.3.2
The missed additional tax benefit has a put-option-shaped payoff: it is zero when the primary ETF price is above the harvest price and rises as that price falls below it. Pricing that potential benefit makes an immediate harvest comparable with its future constraint. section 14.3.2
VTI and ITOT replacement
After selling VTI at a loss and buying ITOT, a further decline may create another harvestable loss. Selling ITOT would require buying VTI, but doing so within 30 days would trigger a wash sale. A 30-day American put, with the ETF price as both spot and strike, estimates the value of this forgone flexibility. section 14.3.2
Figure 14.5 Potential additional tax benefit as a function of VTI’s price
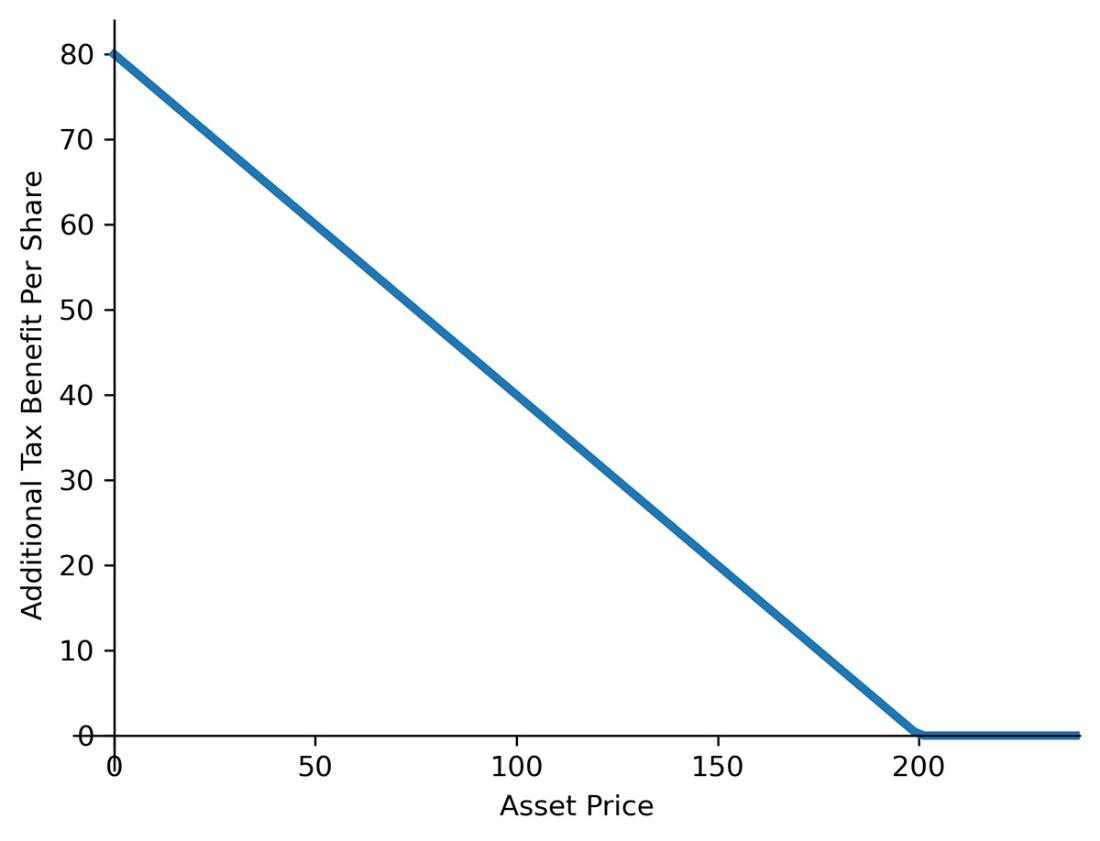
The payoff plot shows why the additional benefit is zero above the harvest price and increases below it, matching a put option’s shape. section 14.3.2
