Option value can quantify the opportunity cost created by a tax-loss harvest. Selling a losing ETF and buying an alternate preserves market exposure, but wash-sale rules can prevent switching back for 30 days. If the replacement ETF falls further, a second harvest may be unavailable; that missed tax benefit has the payoff shape of a put option. section 14.3.2
VTI–ITOT replacement
Buy 10 VTI shares at $200, sell at $190 to harvest the loss, and buy ITOT at $190. If both later fall to $170, harvesting ITOT would require replacing it with VTI, but buying VTI within 30 days triggers a wash sale. The foregone additional tax benefit grows as the primary ETF price falls below the earlier harvest price. section 14.3.2
Estimate this cost as an American put with the current price and strike set to the harvest price, a 30-day term, volatility, risk-free rate, and dividend yield. Compare the resulting option price with the immediate tax benefit when deciding whether a loss is worth harvesting. section 14.3.2
Figure 14.5 Potential additional tax benefit as a function of VTI’s price
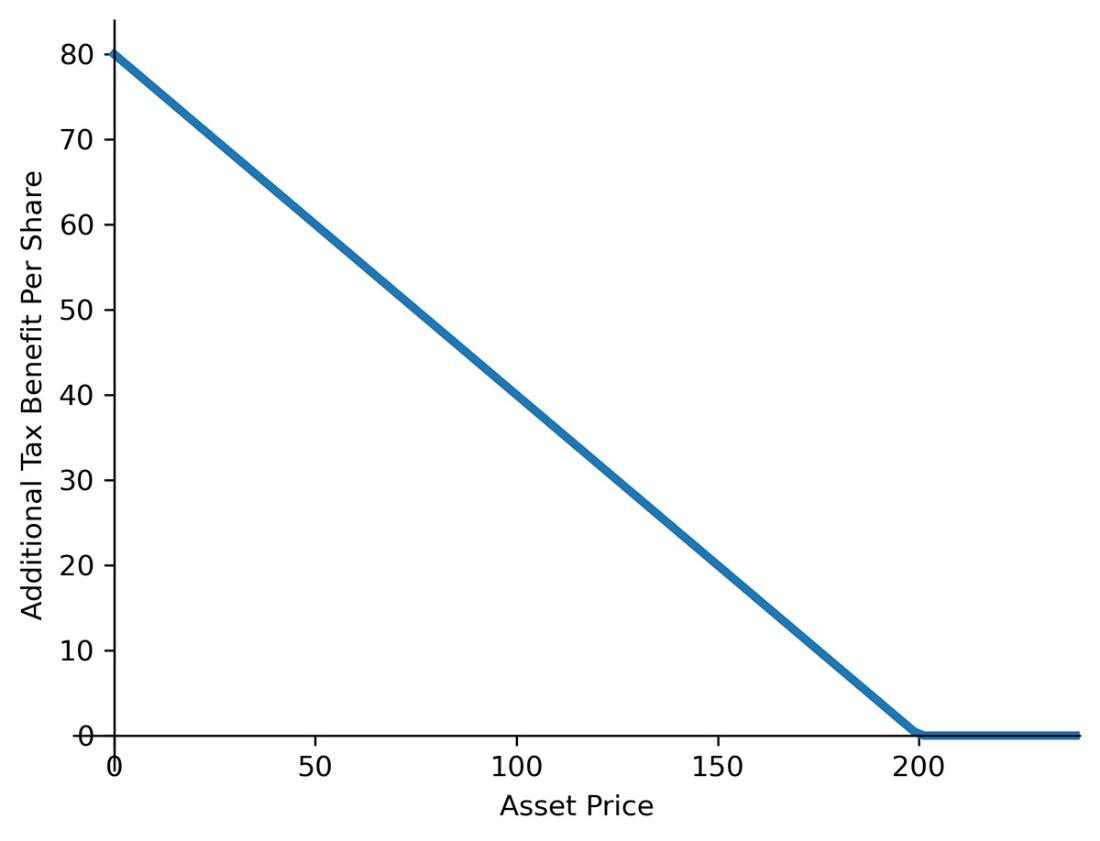
The payoff plot shows why the missed benefit is zero above the harvest price and rises linearly below it. section 14.3.2
