Conformal prediction is a nonparametric, model-agnostic framework for quantifying forecast uncertainty without assuming a fixed statistical distribution. A user-specified confidence level controls the intended proportion of actual values inside the prediction interval. section 3.2.2
The method uses historical predictions and actual values to calculate conformity scores, such as absolute errors. It adds and subtracts these scores from each point forecast, then uses quantiles to form intervals. Its central assumption is exchangeability; die rolls illustrate this assumption, whereas time-series order does not satisfy it directly. section 3.2.2
Figure 3.4 Overview of conformal prediction for time-series data. Historical predictions are used to calculate conformity scores, which are used to generate a range of possible values for each point forecast. From that range of possible values, we calculate the quantiles corresponding to a user-specified confidence level.
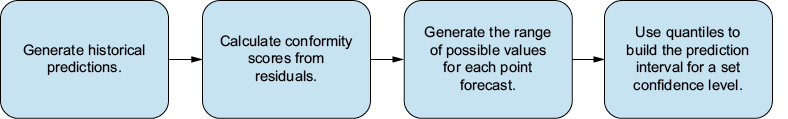
Trace the time-series workflow from historical predictions and conformity scores to quantiles and prediction intervals. section 3.2.2
A practical anomaly-detection workflow:
- Configure PredictionIntervals with a confidence level, run cross-validation, and refit the forecasting model at every window. section 9.5 section 9.5.1
- Flag an observation as anomalous when it falls below the lower interval or above the upper interval. section 9.5.1
- Treat interval calibration and computational cost as practical trade-offs: short training produced many false anomalies and low precision. section 9.5.1
Website visits and taxi rides
For a forecast of 300 daily website visits, an 80% interval might span 200–400, while a 90% interval might span 100–500. In anomaly detection, conformal intervals applied to daily New York City taxi rides identify values outside a 99% interval, though poorly calibrated intervals can overflag normal observations. section 3.2.2 section 9.5.1
