TimeGPT is a proprietary foundation model for time-series forecasting and related analysis. It is a pretrained generative transformer trained on 100 billion data points from domains including finance, demographics, health care, and energy. section 3.10 section 3.2.1
At its core, TimeGPT is a full encoder–decoder transformer that models the conditional probability of future values from past target values and, when supplied, past and future exogenous features. This makes it probabilistic rather than merely point-predictive. section 3.2
(3.1)
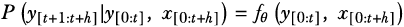
Use the conditional-distribution formulation to relate historical observations, forecast horizons, and exogenous variables. section 3.2
TimeGPT is accessed remotely rather than downloaded locally. The usual workflow loads data, initializes NixtlaClient with an API token, and calls methods for forecasting, cross-validation, or anomaly detection. Data generally uses unique_id for series identity, ds for timestamps, and y for targets, although custom column names can be specified. section 3.3 section 3.3.1
Common TimeGPT operations include:
- Generate zero-shot forecasts for one or multiple series in parallel while automatically inferring timestamp frequency. section 3.3.2
- Fine-tune on a task dataset by specifying training steps and a loss function. section 3.4 section 3.10
- Use exogenous variables through future feature values, recognizing that dynamic covariates must themselves be forecast over the requested horizon. section 3.2 section 3.5.2
- Evaluate forecasts with held-out data, MAE, sMAPE, and cross-validation rather than judging predictions without observed future values. section 3.3.3 section 10.2.4
- Forecast long horizons with timegpt-1-long-horizon, which performed better than the base model in a 52-week sales comparison. section 3.7
- Detect anomalies by generating historical forecasts and labeling observations outside a prediction interval. section 3.8 section 3.8.1
Weekly store-sales forecasting
A dataset containing weekly sales for four Walmart stores can be split into input and eight-week test sets. A zero-shot forecast averaged an MAE of about $54,047 and an sMAPE of 1.76% across stores. In that experiment, adding exogenous features did not improve the baseline; forecasting those features introduced additional error, and fine-tuning without them performed best among the compared methods. section 3.0 section 3.3.3 section 3.5.4
Remote access removes the need for local model hardware, but introduces dependence on internet connectivity, server availability, latency, subscriptions, and API usage limits. The proprietary model cannot be downloaded for local use. Anomaly detection cannot cover the initial input sequence, and a narrower prediction interval detects more anomalies at the cost of lower precision. section 3.3 section 3.10 section 3.8.1
