Fundamental data describes a company through relatively slow-changing accounting information, including quarterly income statements, balance sheets, and cash flow statements. Unlike technical data, it does not require rapid delivery, but reported figures still require skepticism because accounting choices can conceal problems or exaggerate profits. section 3.1
A practical collection workflow treats fundamental data as filed corporate information:
- Prefer accounting statements filed with regulators or other originating entities. section 3.5
- Use financial data providers when aggregating filings across countries, exchanges, and differing APIs or standards. section 3.5
- Keep collection reproducible and deterministic rather than treating generative AI as a replacement for data acquisition. section 3.5
Figure 3.7 In a slightly simplified way, users can collect data from financial data providers, who collect technical data from one or more exchanges per country and one regulator per country.
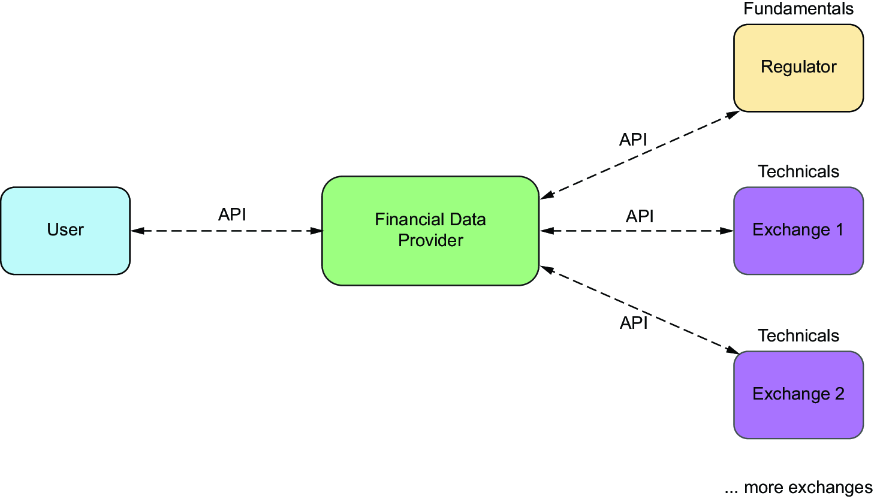
Trace how regulators and exchanges supply data to financial providers, which then serve users. section 3.5

