At a BNPL checkout or during a corporate loan negotiation, underwriting determines who receives credit, on what terms, and why. It is the pre-loan decision stage of the loan life cycle. section 4.2.1
The checks depend on the borrower:
- Personal credit starts with Know Your Customer (KYC) identity checks. Risk evaluation typically uses credit bureau data and transaction history; thin-file borrowers may require alternative data. section 4.2.1
- Corporate credit adds Know Your Business (KYB) checks of incorporation, beneficial owners, and directors. Risk evaluation considers balance sheets, liquidity, collateral, and possible director guarantees. section 4.2.1
AI can accelerate document checks, flag anomalies, and support models that predict default probability. These tools support distinct identification and credit-evaluation tasks rather than replacing the decision process. section 4.2.1
Figure 4.1 The three key phases of the loan life cycle, pre-loan, in-loan, and post-loan, apply to both personal and corporate credit products. Each phase contains distinct activities, decision points, and opportunities for AI-enhanced risk management.
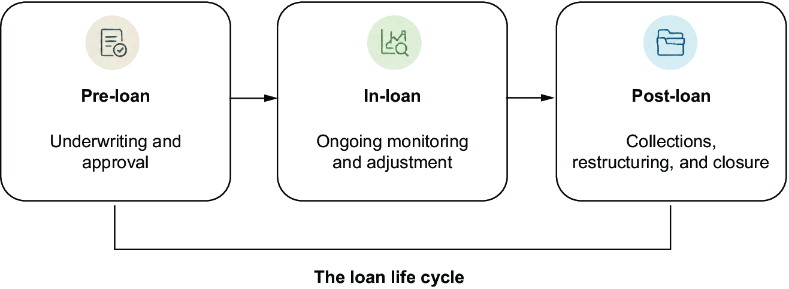
Places underwriting in the pre-loan phase alongside the later in-loan and post-loan phases. section 4.2.1
