Multicollinearity is strong correlation among independent variables in a regression model. It is a linear-regression assumption because correlated predictors can affect the accuracy and interpretation of model outputs. section 4.3.2 section 9.2.2
Assess multicollinearity during exploratory analysis and model evaluation:
- Review correlations among independent variables and identify strongly correlated predictors. section 4.3.2 section 9.2.1
- Select between variables when strong correlations indicate that one predictor adds little new information. section 4.3.2 section 9.2.1
- Compare predictor effects in the fitted model with correlation results to judge whether remaining collinearity affects predictions. section 9.2.2
Weather and rat-sighting predictors
Monthly temperature patterns may make month redundant with daily high temperature, so month can be excluded. Day of week adds a distinct behavioral pattern and is unlikely to introduce collinearity with temperature or wind speed. section 9.2.1
Figure 9.25 Correlation matrix including the new binary weekday column.
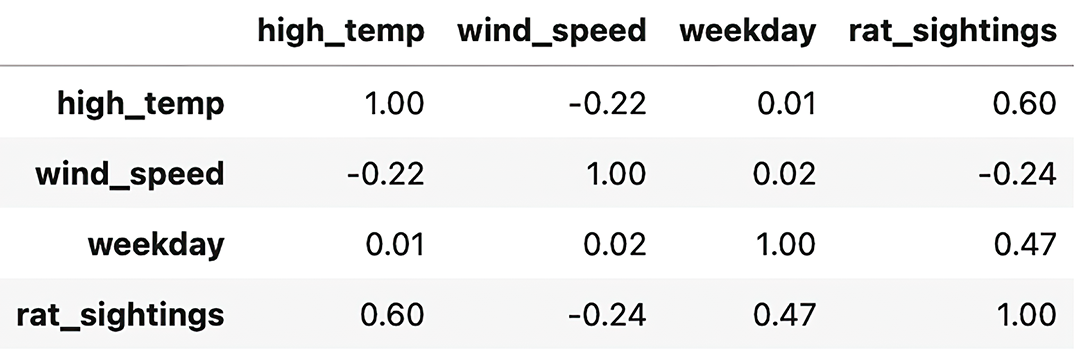
Use the correlation matrix to inspect relationships among high temperature, wind speed, weekday, and rat sightings. section 9.2.1






