liveBook · Manning

Mean squared error

As explained in Time Series Forecasting Using Foundation Models

Mean squared error is the average of the squared differences between predicted and actual values.

Mean squared error (MSE) averages the squared differences between predicted and actual values. Squaring makes large errors count more heavily, making MSE useful as a loss for deterministic point-forecasting models such as TimesFM. section 7.1 section 7.1.2

(7.1)
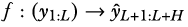
A diagram of a machine

Description automatically generated

Use the equation to connect the average squared prediction error with the training objective for deterministic forecasts. section 7.1


How Time Series Forecasting Using Foundation Models covers it

How deep it goes
Defines the metric and explains its error weighting, but does not develop implementation or comparative evaluation procedures.
Examples
Uses TimesFM pretraining as the concrete example, with MSE minimizing errors across large time-series datasets.
What you can do after
Evaluate understanding of why large forecasting errors receive disproportionate penalties under MSE.
How it connects
Connects MSE with deterministic forecasting, point forecasts, loss functions, and mean absolute error.

Also explained in

Compare how 13 books explain mean squared error →

Related concepts

This explainer was generated by Manning's knowledge graph from the text of Time Series Forecasting Using Foundation Models. The section links point to the parts of the book it draws on.










