Covariance measures how two random variables vary together. In a multivariate Gaussian, the covariance matrix captures both each variable’s variance and the relationships between variables. section 2.2.1
Read the covariance matrix by position:
- Diagonal entries give the variances of the individual random variables. section 2.2.1
- Off-diagonal entries give the covariance between pairs of variables and relate to their correlation. section 2.2.1
- Positive covariance indicates that variables tend to move together; stronger positive correlation indicates a closer relationship. section 2.2.1
Figure 2.4 An MVN distribution groups multiple normally distributed random variables together. While the mean vector of the MVN concatenates the mean values, the covariance matrix models the correlations between the individual variables.
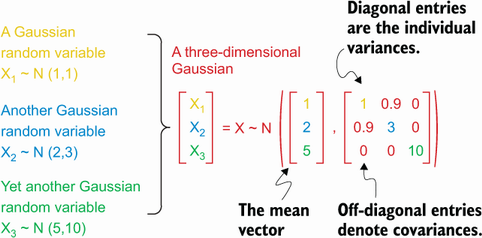
Use the figure to see how a mean vector represents individual variables while the covariance matrix represents their relationships. section 2.2.1




